Key takeaways
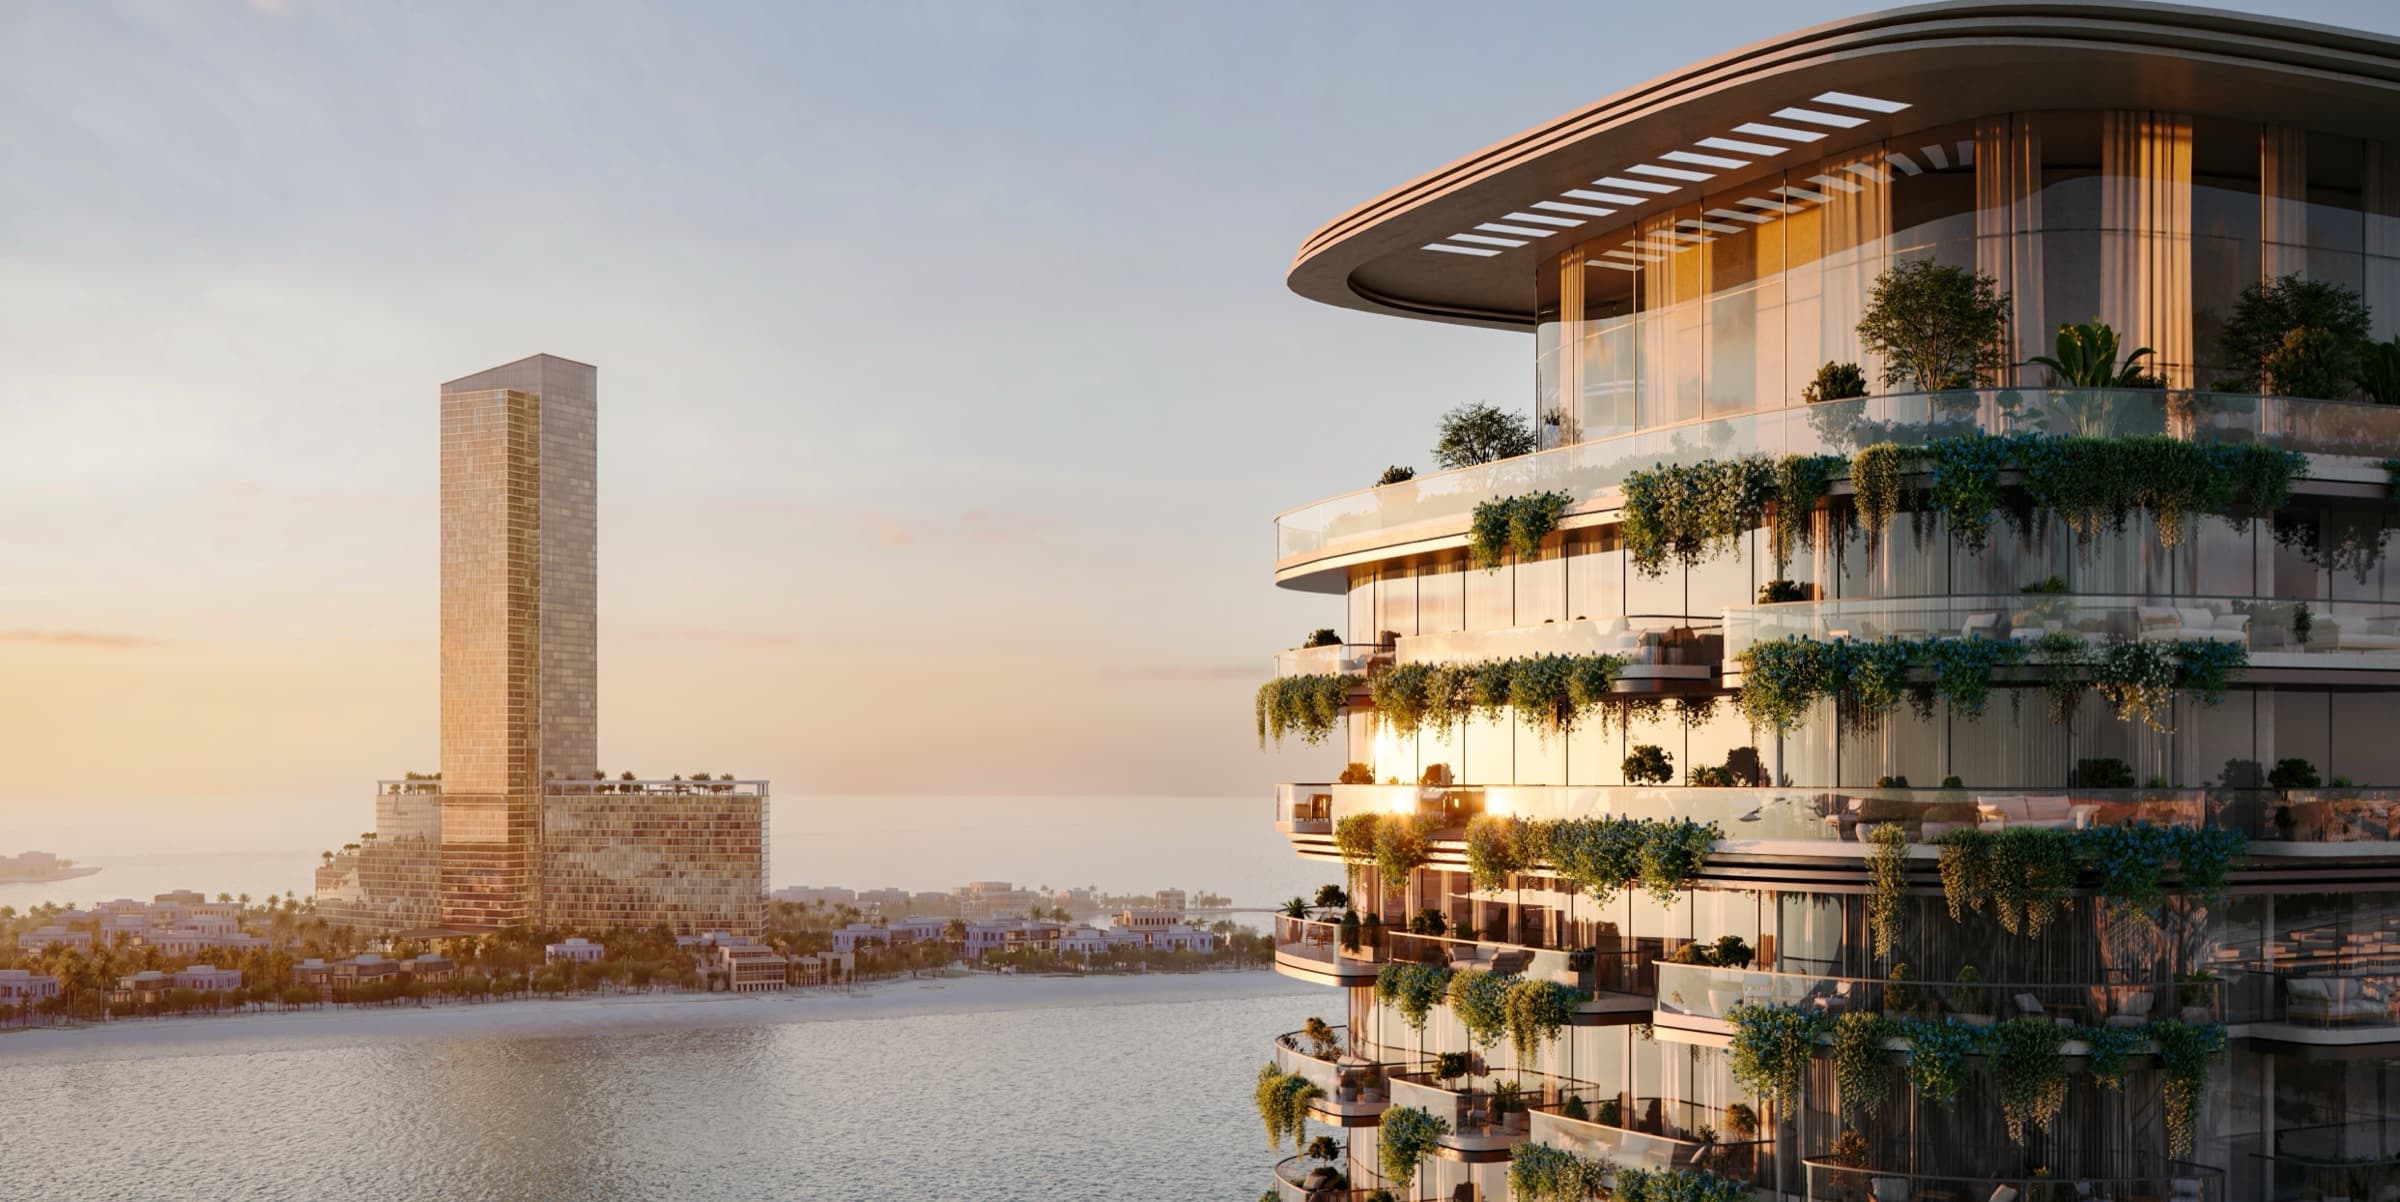
- District One Dubai is the front-lagoon district of MBR City, built around a 7 km² Crystal Lagoon, one of the largest artificial urban lagoons in the world
- Villas trade between AED 28,000 and 35,000/sqm, apartments between AED 22,000 and 27,000/sqm — levels close to Palm Jumeirah for a newer product
- Estimated gross yield sits between 4.5% and 5.5%, 2 to 3 points below Meydan (7-8%): District One plays on capital appreciation, not cash flow
- Entry price exceeds AED 12M for a standalone villa, starting around AED 2M for an apartment, a threshold that unlocks the 10-year Golden Visa
- 0% UAE tax on rent and capital gains changes the math: a 5% gross yield in Dubai clearly beats a 5% yield in Paris taxed at 30-47% in France
- For pure cash flow within MBR City, the better trade-off sits in Meydan or Sobha Hartland, two sub-markets with a more aggressive yield profile
What rental yield can you expect at District One in 2026?
Gross yield at District One runs between 4.5% and 5.5% in 2026. It depends on property type and proximity to the lagoon. Front-lagoon villas pull yield toward the lower end. Their price per sqm is the highest, but rent doesn't scale proportionally. Apartments, cheaper per sqm, sit closer to the top of the range.
4.5% - 5.5%District One gross yield 2026 · DLD / Property Monitor 2025-2026This figure remains structurally behind District One's immediate MBR City neighbours. Sobha Hartland delivers 6-7% gross, Meydan 7-8%. The gap comes down to the denominator. Scarce lagoon-front land drives up purchase price. Meanwhile, the villa rental market stays narrow and can't absorb a matching rent increase.
Gross, net, and what 0% tax really changes
Moving from gross to net absorbs a meaningful share of the headline yield. Service charges run high on front-lagoon villas: lagoon upkeep, 24/7 security, gardens, facades. Property management takes 5-8% of collected rent. DEWA and chiller costs add up on top, on private units, separate from shared charges.
The typical District One tenant isn't a fast-turnover profile. Think senior expat family, executive, corporate lease. Terms run long, and vacancy stays low. The trade-off: rent renegotiation follows the slower pace of the RERA rental index, not a tight rental market like Meydan.
Against that backdrop, zero tax on rental income and capital gains in France, Belgium or Switzerland doesn't offset a 2-3 point gross yield gap. But it does fully play out on capital stability and medium-term appreciation. This is a wealth-planning trade-off, not a cash-flow calculation.
The verdict depends on investor profile. For immediate cash flow, Meydan stays more efficient. For a wealth-preservation asset, District One keeps its own case within MBR City. That's thanks to a guaranteed Golden Visa (the AED 2M threshold is easily cleared) and rare lagoon exposure.
What does a square metre cost at District One, tower by tower?
The zone-wide range masks a sharp gap between property types. Standalone 4-7 bedroom villas, built in the early phases toward Wadi Al Safa, trade between AED 28,000 and 35,000/sqm. The top of that range is reserved for plots directly on the lagoon.
AED 28,000-35,000/sqmFront-lagoon villas · Dubai Land Department / market data 2026Recent apartments, led by District One Residences, trade between AED 22,000 and 27,000/sqm. The gap versus villas reaches 20-30% at the same address. That reflects villa land scarcity more than any difference in build quality.
Mansions escape any per-sqm pricing grid entirely. They're negotiated case by case, based on plot size and lagoon frontage length, closer to a land transaction than a standard property purchase.
Table: price, yield, and entry price by property type
| Type | Price per sqm | Estimated gross yield | Indicative entry price |
|---|---|---|---|
| 4-7 bed villas (front-lagoon) | AED 32,000-35,000/sqm | 4-4.5% | ~AED 8-14M |
| 4-7 bed villas (2nd row) | AED 28,000-30,000/sqm | 4.5-5% | ~AED 6-10M |
| Apartments / District One Residences | AED 22,000-27,000/sqm | 5-5.5% | ~AED 1.8-3.5M |
| Mansions | negotiated per plot | non-standardised | AED 20M and above |
Position dominates every other pricing factor. The front-lagoon premium versus second row weighs more heavily on final price than year of delivery. That's consistent with the district's wealth-preservation positioning, built around its
7 km² Crystal Lagoon, one of the largest artificial urban lagoons in the world
.
To verify these figures yourself, the method stays simple. Query the Dubai Land Department transactional portal by building and period, then strip out off-plan sales to isolate the secondary market. That avoids mixing developer launch pricing with actual resale prices.
For detailed building-by-building data, our dedicated guide goes further: District One Residences, prices and yields 2026.
Who buys at District One, and why?
District One doesn't attract a yield-hunter profile. Gross yield of 4.5-5.5% puts it behind Sobha Hartland and Meydan. The typical buyer is an HNW family, often a UAE tax resident, seeking a tangible mixed-use asset: primary or secondary home, plus a store of value. The 7 km² lagoon and the scarcity of front-lagoon plots play a wealth-preservation role here, not a cash-flow role.
The Golden Visa isn't a differentiating feature of this specific district, contrary to what's sometimes claimed.
A property asset worth AED 2M unlocks eligibility for the 10-year Golden Visa, a threshold met by nearly all District One units.
The visa comes as a byproduct of the purchase, not a bonus to negotiate separately.
For French-speaking buyers purchasing remotely — from France, Belgium, Switzerland, Canada — the deal often runs by power of attorney: remote notarised signature, local bank account opening, coordination with notary and bank. That's precisely the kind of process we handle for our clients through our services.
For American and Israeli buyers, UAE tax neutrality doesn't remove reporting obligations in the country of residence: the IRS for one, local tax authorities for the other. That's a point to address upfront, not after signing.
Demand signals stay strong: 18.72 million international visitors in 2024, a record that fuels premium residential demand (Dubai Department of Economy and Tourism). Resale liquidity, though, takes patience. The buyer pool is narrow but deep in value, with a longer marketing timeline than an apartment in Meydan.
District One, Sobha Hartland, or Meydan: which one to choose?
The choice comes down to three variables: entry price, holding horizon, primary objective. Capital or cash flow, not both at once.
District One requires an entry price from AED 5M, over a 7-10 year horizon. The goal is capital appreciation and personal use, not immediate yield. Gross yield sits between 4.5% and 5.5%.
Sobha Hartland positions itself as a middle ground. Entry price around AED 1.8M, price per sqm of AED 22,000-26,000 new, gross yield of 6-7%. Post-handover payment plans ease the cash burden at purchase.
Meydan targets cash flow. Entry price close to AED 1.2M, price per sqm of AED 18,000-22,000, gross yield of 7-8% on studios and 1BRs. Higher rental turnover, a clearly income-oriented profile.
| Criterion | District One | Sobha Hartland | Meydan |
|---|---|---|---|
| Entry price | AED 5M+ | ~AED 1.8M | ~AED 1.2M |
| Price/sqm (new) | AED 22,000-35,000 | AED 22,000-26,000 | AED 18,000-22,000 |
| Gross yield | 4.5-5.5% | 6-7% | 7-8% |
| Horizon | 7-10 years | 5-7 years | 3-5 years |
| Objective | Capital, personal use | Middle ground | Cash flow |
Simple rule: if the objective is income, District One isn't the right door within MBR City. Villa-type detail on Meydan is covered in our guide to Jumeirah Park for a comparable villa logic. This is precisely the entry price/horizon/objective trade-off we frame with our clients before any project shortlist.
Outlook 2026-2028: what will the lagoon be worth long term?
District One's front-lagoon land is finite by design. No extension to the Crystal Lagoon is planned. This structural scarcity is the main long-term argument for this sub-market.
MBR City's pipeline stays massive: more than AED 45 billion announced by Sobha Realty, Meydan Group, Nakheel and Emaar, per developer communications, with phased deliveries through 2026-2028. But most of that volume is being built on MBR City's periphery, not on the lagoon's shores itself. Competing supply raises the district's overall volume without diluting front-lagoon scarcity.
This knock-on effect actually favours District One: the area's rising standing, driven by Meydan One Mall and the Business Bay-Meydan corridor, reinforces the premium positioning of all of MBR City, lagoon included.
The honest risk to flag: the front-lagoon premium is sensitive to a slowdown in the ultra-luxury segment, and a villa always trades more slowly than an apartment. This isn't an asset for anyone who needs a fast exit.
For an owner who wants to liquidate quickly without exposing their property to the open market, a firm offer within 48 hours remains an off-market alternative, even for a slower-moving front-lagoon asset.
Go further
Three related reads from the Level8 journal:
- Bugatti Residences Dubai: the real investment case in 2026 — Bugatti Residences Dubai broken down for investors: price per sqm, payment plan, rental yield, and comparison with Armani, Cavalli and Mercedes-Benz Places.
- Al Reem Island: 49% of Abu Dhabi's off-plan sales this summer — Yes, Al Reem Island dominates Abu Dhabi's off-plan market: 1,291 of the 2,658 off-plan apartment sales in summer 2026, or 49%. Sold floor area has quadrupled in two years, according to MERED.
- Dubai Jumeirah Park: how to buy a villa in 2026 — A step-by-step guide to buying a villa in Dubai Jumeirah Park in 2026: DLD process, escrow, ancillary costs, 3-4BR yields, and off-plan vs resale trade-offs.
FAQ
What's the minimum budget to invest at District One in 2026?
Entry price starts around AED 1.8-2M for an apartment in District One Residences, and exceeds AED 12M for a standalone 2nd-row villa. That AED 2M threshold unlocks eligibility for the 10-year Golden Visa under DLD criteria.
Does District One qualify for the Golden Visa?
Yes, any acquisition from AED 2M in a completed property, or an off-plan unit validated by the Dubai Land Department, unlocks eligibility for the 10-year Golden Visa. At District One, entry price clears this threshold by a wide margin, apartments included.
Why is District One's yield lower than Meydan's or Sobha Hartland's?
The high price per sqm, driven by front-lagoon land scarcity, inflates the yield calculation's denominator. The villa rental market stays narrow and can't absorb a proportional rent increase. That caps gross yield between 4.5% and 5.5%, versus 7-8% at Meydan.
How does District One's tax treatment compare to investing in France?
Rent and capital gains earned in Dubai face no income tax or capital gains levy, unlike France, where an equivalent gross yield is taxed between 30% and 47%. That gap favours the net return for a French, Belgian or Swiss resident investor, even at a lower gross yield than Meydan.
Should you buy off-plan or on the secondary market at District One?
The secondary market lets you verify a real rental track record via the Dubai Land Department's transactional portal, filtered by building and period. Off-plan still makes sense on recent District One Residences phases, with a staged payment plan and funds secured in an escrow account.
What's the yield gap between a front-lagoon villa and an apartment at District One?
Front-lagoon villas post the lowest yield, around 4-4.5% gross, since their price per sqm reaches AED 32,000-35,000. Apartments, at AED 22,000-27,000/sqm, sit closer to 5-5.5% gross, a gap that mainly reflects villa land scarcity.
Sources
The figures and rules quoted in this article come from the following sources :